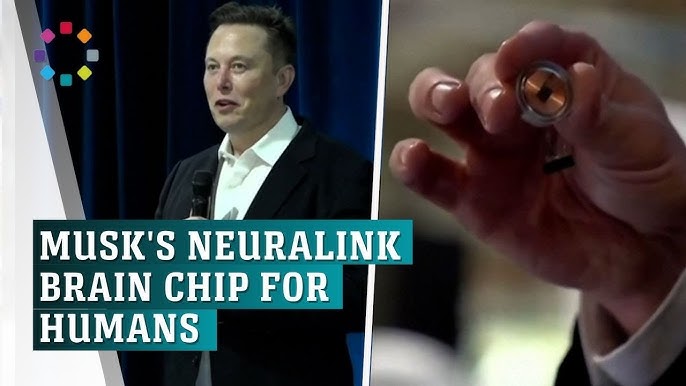
Neuralink is no longer a science project. It is transitioning into a vertically integrated neurotechnology platform with early clinical validation, manufacturing scale ambitions, and a credible path toward becoming one of the most important companies of the next decade.

Curing Dementia, ALS is the mission.
G.L.A INVE$T RESEARCH
PRIVATE MARKET STOCK SPOTLIGHT: NEURALINK
Neuralink is building a high-bandwidth brain-computer interface (BCI) platform designed to connect the human brain directly to machines. Initially focused on restoring function for patients with paralysis, ALS, and neurological disorders, the long-term vision extends into human-AI symbiosis, cognitive enhancement, and direct “telepathic” communication.
Latest private valuation: ~ $8B–$9B
Employees: ~300+
Clinical patients: 25+ implanted (rapidly scaling)
Stage: Early commercialization / clinical expansion

The Problem Neuralink Solves
Neuralink is attacking one of the largest and most under-addressed problem spaces globally:
Over 40% of the population suffers from neurological conditions
Paralysis, ALS, blindness, and dementia remain largely unsolved
Human communication bandwidth is extremely limited (speech/typing bottleneck)
Neuralink addresses both:
Immediate medical needs (restoring function)
Long-term human evolution (brain-AI integration)
Example: A fully paralyzed patient can now control a computer and wheelchair purely through thought—regaining independence after years of immobility.
Neuralink — Pioneering Brain Computer Interfaces
Creating a generalized brain interface to restore autonomy to those with unmet medical needs today and unlock human potential tomorrow.
Neuralink • Neuralink
Product & Technology
Neuralink’s core system includes:
Implantable brain chip (high channel count neural interface)
Ultra-thin electrode threads inserted into cortex
Surgical robot for precision implantation
AI-driven decoding software
Proprietary chip + packaging (new PCTF polymer enclosure breakthrough)
Recent breakthroughs:
Trans-dural implantation (no cutting of dura → safer, faster, scalable)
High-density electrode packaging (massive signal improvement)
Neural data training for AI models (future moat layer)
Potential early-stage “telepathic communication” experiments
This is not a single product—it is a full-stack neurotechnology platform.

Founder & Leadership
Elon Musk (Founder)
One of the strongest founder advantages in private markets:
Tesla → manufacturing + AI + chips
SpaceX → vertical integration + engineering culture
xAI → AI models + compute
Neuralink benefits from all three ecosystems
President DJ Seo emphasizes:
Vertical integration as core strategy
Scale-first thinking from Day 1
LASIK-style surgery ambition (millions per year)
This is classic Musk playbook: build the machine that builds the machine.

Notable Investors
Founders Fund (Peter Thiel network proximity)
Sequoia Capital (via ecosystem exposure/interviews)
High alignment with elite Silicon Valley capital
Neuralink sits inside the highest quality investor/founder network globally.

Business Model & Growth
Current phase: Clinical validation → early scaling
Near-term revenue:
Medical device + procedure (insured eventually)
Clinics + surgical platform
Mid-term:
Software + neural interface platform
Data + AI-driven diagnostics
Long-term:
Cognitive enhancement
Brain-to-brain / brain-to-AI communication
Potential subscription ecosystem
Growth signals:

Honorable Mention: EREBOR, BORING COMPANY, D-MATRIX, Prometheus
Expanding patient base globally
New geographies (Canada, UAE trials)
Manufacturing scaling (Samsung chip partnership)
Facility expansion (Austin campus, SF, Fremont)

Total Addressable Market (TAM)
This is one of the largest TAMs in history:
Neurological disorders: $500B+ global impact
Assistive technologies: $100B+
Human-computer interface evolution: multi-trillion
AI-human integration: effectively uncapped
If successful, Neuralink is not a medical device company—it is a new computing platform.
Moat Analysis
Neuralink’s moat is exceptionally strong and multi-layered:
Hardware complexity (implant + threads + chip)
Surgical robotics (extremely hard to replicate)
Data moat (neural datasets → foundation models)
Vertical integration (design → manufacturing → surgery)
Regulatory + clinical head start
Elon Musk ecosystem advantage
The real long-term moat: proprietary brain data + AI models trained on it.

Maybe they can cure my ADHD!!
Competitive Landscape
China (e.g., Neucyber/Nuracle): faster regulatory scaling, lower complexity devices
Meta: non-invasive brain decoding
Snap / Apple / Google: AR wearables (lower fidelity)
Private Market Price History (Estimates)
2023: ~$5B valuation
2024: ~$7B
2025: ~$8B–$9B
Path to Exit
Three realistic paths:
IPO (most likely)
Positioned as both medtech + AI platform
Could command premium multiple
Strategic dominance (remain private longer like SpaceX)
Driven by Musk preference
MERGES WITH SPCX/TSLA into 1 conglomerate

THE G.A.U.N.T.L.E.T SCORING SYSTEM
Size & Predictability:7/10
Early revenue, but massive visibility into demandVisionary Founder: 10/10
Elon Musk is a generational outlierMust-Have Product: 10/10
Life-changing for patients, eventually essential for humansHyper Growth + Financial Position: 8/10
Pre-revenue scale, but positioned for explosive adoptionTAM: 10/10
Arguably one of the largest TAMs everMoat Strength: 10/10
Deep tech + data + vertical integrationRisk vs Reward:9/10
High risk, asymmetric upside (trillion-dollar potential)Solving Major Problems: 10/10
Directly addresses human suffering and cognitionInvestor Quality: 9/10
Top-tier networks and capitalWall Street Misunderstanding: 10/10
Still widely underestimated and misunderstood
Final GAUNTLET Score: 93 / 100- VERY High
G.L.A INVEST Verdict
Neuralink is one of the highest-upside investments in the private market today.
It passes the GAUNTLET with elite scores across nearly every category. The combination of:
Founder quality
Market size
Technical moat
Early real-world validation
creates a rare asymmetric opportunity.
This is not just a medtech company—it is a foundational layer for the future of human-computer interaction.
The biggest risk is not competition.
It is execution speed vs regulation and public perception.
If Neuralink succeeds, it will not be a $100B company.
It will be a platform measured in trillions.

COACH KYLE’s 2 CENTS: NEURALINK like SPACEX is an Investment that will be handed down to future generations, I view it as a must BUY.