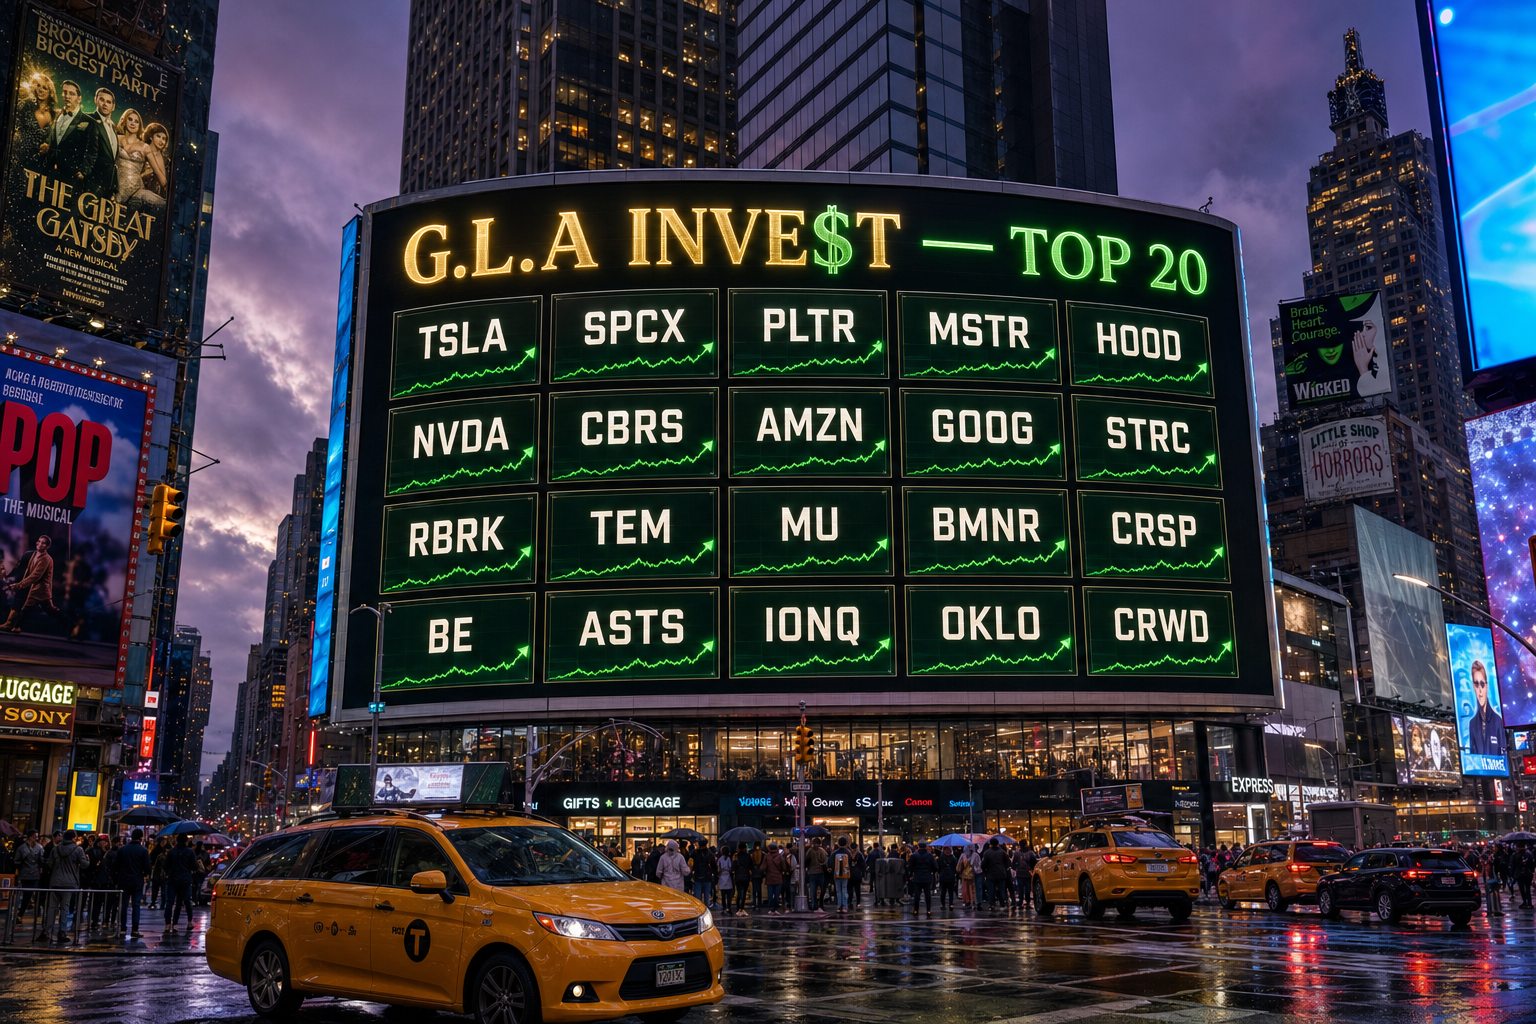
G.L.A INVE$T RE$EARCH & Coach Kyle Present
THE INFINITE INNOVATION NEWSLETTER

G.L.A TOP 20 UPDATE/OUTLOOK — August 27, 2026
Long-Term Exponential Growth Ideas for the Innovation Investor
DISCLAIMER: G.L.A INVE$T RE$EARCH and Coach Kyle are not licensed financial advisors, broker-dealers, or investment professionals. Nothing in this newsletter constitutes investment advice, a recommendation to buy or sell any security, or a solicitation of any kind. This publication is created strictly for educational and informational purposes. All content reflects publicly available data and personal opinion. Innovation and exponential-growth investing — in the tradition of firms like ARK Invest and analysts like Tom Lee — requires significant volatility tolerance, patience, and long-term conviction. Past performance and price targets from third parties are not indicative of future results. Always do your own research and consult a licensed financial professional before making investment decisions.
The G.L.A MISSION
Our mission is to keep our network “in the know” with what’s really going on with the stock market and its best longterm investments. Through our family of newsletters and 1 on 1 coaching calls we provide breaking news, news translations, deep dive research reports, independent experienced perspectives and insights of a 25 year wall st veteran and former broker.
Snapshot: G.L.A Top 20
Ticker | Company | Price | Mkt Cap | Theme |
|---|---|---|---|---|
TSLA | Tesla | $354.30 | $1.40T | EVs, robotics, autonomy, energy |
SPCX | SpaceX | ~$140 | — | Launch, Starlink, AI infrastructure |
PLTR | Palantir | $185.22 | $425B | AI/defense software |
MSTR | Strategy | $138.53 | $45.8B | Bitcoin treasury + software |
HOOD | Robinhood | $110.64 | $99.5B | Retail trading, crypto, fintech |
NVDA | Nvidia | $229.26 | $5.55T | AI compute/GPUs |
CBRS | Cerebras | $182.17 | $41.3B | AI wafer-scale chips |
AMZN | Amazon | $255.98 | $2.75T | Cloud, e-commerce, AI |
GOOG | Alphabet | $338.38 | $4.11T | Search, cloud, AI, quantum |
STRC | Strategy Preferred | $98.02 | $33.8B | High-yield BTC-linked income |
RBRK | Rubrik | $106.77 | $22.0B | Data security/cyber recovery |
TEM | Tempus AI | $70.97 | $12.4B | AI precision medicine |
MU | Micron | $914.21 | $1.03T | Memory chips, AI infrastructure |
BMNR | Bitmine Immersion | $26.36 | $15.0B | Ethereum treasury |
CRSP | CRISPR Therapeutics | $59.99 | $5.79B | Gene editing |
BE | Bloom Energy | $220.01 | $64.8B | Fuel cells, AI power |
ASTS | AST SpaceMobile | $60.92 | $24.8B | Satellite-direct-to-phone |
IONQ | IonQ | $42.36 | $15.8B | Quantum computing |
OKLO | Oklo | $43.21 | $7.52B | Advanced fission/SMRs |
CRWD | CrowdStrike | $225.84 | $230B | Cloud-native cybersecurity |
Tesla (TSLA)

Business & Moat: As we know, Tesla is far more than an automaker — it spans EVs, energy storage/generation, and increasingly robotics and autonomy through Optimus and Full Self-Driving. Its moat rests on manufacturing scale, the Supercharger network, in-house battery/chip design, and a data advantage from millions of miles driven that feeds its autonomy models, not to mention the most talented engineers on the planet lead by the greatest innovator of our time ELON MUSK.

Recent Earnings & Catalysts: Shares trade near $354 with a market cap around $1.4 trillion and a rich forward-looking P/E of ~328, reflecting the market’s pricing of future robotics/autonomy optionality rather than current auto margins. ARK Invest’s open-source Tesla model has pegged a 2026 expected value in the thousands of dollars per pre-split share (~$1,533 post-split expected case, with bull/bear ranges), driven by robotaxi and humanoid robot deployment assumptions. IMHO the current narrative with TESLA is no where near the actual reality, this is why it’s my top choice, once the masses figure out the multiple check mates Tesla holds the stock should rip.

His Mission Is To Create Sustainable Abundance For All Humans, How Can Anyone Argue with That?
Founder & TAM: Elon Musk aka the founder of all founders, continues to run Tesla alongside SpaceX. The long-term TAM spans the ~$4 trillion global auto market, grid-scale energy storage, and a nascent humanoid robotics market some see exceeding $10 trillion by the 2030s-2040s.
Why Long-Term: Tesla is working on the 3 largest AI projects on earth- CYBERCAB/FSD, TERRAFAB, OPTIMUS HUMANOID ROBOT. Timelines aside, these projects will happen, also a merger with SPACEX is likely as well. The combined company is setup to be the best longterm investment ever. We are betting on ELON and his group of the most talented mission driven engineers.
SpaceX (SPCX)

Business & Moat: SpaceX operates across three segments — reusable-rocket launch services, Starlink satellite connectivity, and an emerging AI compute segment. Its moat is reusability (Falcon 9, and eventually Starship), which has driven launch costs down an order of magnitude versus legacy competitors, plus a dominant global satellite constellation which has been adding 20k new subscribers per day.
Recent Earnings & Catalysts: Newly public post-IPO (June 2026, priced at $135), shares trade around $140. Starlink crossed roughly 12 million subscribers by mid-2026, though average revenue per user has been declining as the company expands into lower-ARPU markets. Starship V3 — carrying satellites “10 times more powerful” than current Starlink hardware — is the key 2026-2027 catalyst that could unlock a step-change in constellation capacity.

Founder & TAM: Founded and led by Elon Musk, SpaceX is chasing TAM across launch services, global broadband, direct-to-cell connectivity, and now AI infrastructure/compute in space. Some analysts project revenue run-rates approaching $60 billion by end of 2026.
Why Long-Term: A rare vertically-integrated space/connectivity/AI compute platform with a first-mover satellite lead — but still early, capital-intensive, and dependent on Starship execution.

SPACEX, X.COM, XAI, STARLINK, TERRAFAB,
Palantir (PLTR)

Business & Moat: Palantir builds Gotham (intelligence/defense analytics), Foundry (enterprise data operating system), and its AI Platform (AIP), which turns LLMs into enterprise-usable tools. Its moat is deep government/defense trust plus a rapidly expanding commercial AIP customer base that’s hard to displace once embedded in mission-critical workflows.
Recent Earnings & Catalysts: Trading at $185.22 with a market cap of $425 billion and a lofty ~157x P/E, Palantir’s valuation prices in continued triple-digit AIP commercial growth. Government AI/defense modernization budgets remain a durable multi-year catalyst.

$PLTR has been in our top 3 since its IPO, and I fully expect it to remain there.
Founder & TAM: Led by CEO Alex Karp, Palantir addresses a TAM spanning defense/intelligence software and the broader enterprise AI software market, projected to reach hundreds of billions of dollars this decade.
Why Long-Term: A pure-play on AI adoption inside government and Fortune 500 enterprises — high valuation risk, but a moat few software peers can match in defense. Palantir thrives in chaos and is an undisruptable company imho.
Strategy / MSTR & STRC (Bitcoin Treasury)
Business & Moat: Strategy Inc (formerly MicroStrategy) operates as the world’s largest corporate Bitcoin treasury while running AI-powered enterprise analytics (Strategy One, Strategy Mosaic). STRC is its preferred stock, paying a variable ~12% annualized dividend pegged near $100 par, engineered to give income-oriented investors Bitcoin-linked yield with less price volatility than the common stock.
Recent Earnings & Catalysts: MSTR trades at $138.53 (market cap $45.8B); STRC trades near $98 with an effective yield around 12%. Tom Lee’s Fundstrat has set long-term Bitcoin targets as high as $200,000-$250,000, with a base case near $150,000, framing 2026 as volatile in H1 before a stronger H2.

Saylor is the ELON of Bitcoin, Bitcoin is the answer to inflation.
Founder & TAM: Founded by Michael Saylor, Strategy’s TAM is essentially Bitcoin’s total addressable store-of-value market, which bulls like Lee argue could scale into the tens of trillions long term.
Why Long-Term: A leveraged proxy on Bitcoin adoption (MSTR) paired with a yield-generating hybrid instrument (STRC) — both require extreme volatility tolerance given crypto’s boom-bust cycles.
Robinhood (HOOD)
Business & Moat: Robinhood’s commission-free brokerage app has evolved into a full financial platform spanning equities, options, crypto, and increasingly banking-like products, with a young, engaged retail user base as its core moat.
Recent Earnings & Catalysts: Q2 2026 revenue came in at $1.31 billion versus $1.29 billion estimated, with EPS of $0.62 beating the $0.43 consensus — a strong beat-and-raise quarter. Shares trade at $110.64 with a market cap of $99.5 billion and a P/E near 49, reflecting rapid growth in trading volumes and crypto activity.cnbc+1
Why Long-Term: Robinhood is riding both the retail-trading boom and crypto adoption wave simultaneously, giving it two structural growth tailwinds, though its results remain sensitive to market volume swings.investing
Nvidia (NVDA)

Business & Moat: Nvidia’s GPUs and CUDA software ecosystem remain the backbone of AI training and inference infrastructure globally, giving it an entrenched hardware-plus-software moat that competitors have struggled to replicate.
Recent Earnings & Catalysts: Trading at $229.26 with a $5.55 trillion market cap and a still-reasonable ~29x P/E given its growth rate, Nvidia continues to benefit from surging AI infrastructure capex across hyperscalers.
Why Long-Term: As the dominant AI compute layer, Nvidia is the picks-and-shovels play on the broader AI buildout that touches nearly every other name on this list.

$NVDA is a very easy choice IMHO
Cerebras Systems (CBRS)

Business & Moat: Cerebras designs wafer-scale AI chips (the CS-3 system) and an AI supercomputer platform, offering an alternative architecture to GPU-based training/inference that claims speed advantages for certain workloads.
Recent Earnings & Catalysts: Shares trade around $182 with a $41.3 billion market cap; notably, ARK Invest bought approximately 93,000 shares of Cerebras in late August 2026, signaling continued innovation-investor conviction. Next year $CBRS revenue is expected to grow over 200% from their 2026 revenue.
Why Long-Term: A high-risk, high-reward specialty AI silicon bet that benefits directly from the same AI infrastructure buildout driving Nvidia and Micron. Inference demand at this point is seemingly infinite, until it ends $CBRS is a buy and hold.
Amazon (AMZN)

Another Founder we love!
Business & Moat: Amazon’s moat spans e-commerce logistics scale, AWS’s cloud infrastructure dominance, and a rapidly growing AI/advertising business layered on top.
Recent Earnings & Catalysts: Trading at $255.98 with a $2.75 trillion market cap and a P/E near 20.6 — inexpensive relative to AI-infrastructure peers — AWS remains the key long-term profit and AI-capex growth driver.
Why Long-Term: A diversified compounder combining defensive retail cash flow with high-growth AWS/AI upside. Big investment in ANTHROPIC is another reason to own AMZN

Alphabet (GOOG)

It doesn’t take a rocket scientist to figure this out. $GOOG is a buy and hold.
Business & Moat: Alphabet’s moat combines Search’s data/distribution advantage, Google Cloud’s growing enterprise footprint, and emerging optionality in quantum computing and AI (Gemini).
Recent Earnings & Catalysts: Shares trade at $338.38 with a $4.11 trillion market cap and a P/E of just 17.15 — cheap relative to AI mega-cap peers, suggesting the market hasn’t fully priced Alphabet’s AI/cloud optionality.
Why Long-Term: Best-in-class AI research (DeepMind/Gemini) combined with a still-dominant advertising cash engine funding future bets.
Rubrik (RBRK)

Business & Moat: Rubrik provides cloud/enterprise data security, backup, and cyber-recovery tools — an increasingly critical layer as ransomware and data breaches proliferate.
Recent Earnings & Catalysts: Q1 FY2027 revenue of $387 million beat estimates ($366 million), with EPS of $0.16 versus a -$0.03 estimate — a meaningful beat-and-swing-to-profitability quarter, though shares remain volatile with expected earnings moves consistently above 10%.
Why Long-Term: Data security spending is structurally non-discretionary, and Rubrik’s recovery-focused niche complements broader cybersecurity plays like CrowdStrike.
Tempus AI (TEM)

$TEM will be one of the companies that will help cure cancer and increase life expectancy for humans.
Business & Moat: Tempus operates an AI-driven precision medicine platform combining genomic sequencing, diagnostics, and a massive proprietary multimodal healthcare dataset licensed to pharma partners including AstraZeneca and Merck.cnbc
Recent Earnings & Catalysts: Q2 2026 revenue of $382 million beat the $380 million estimate; shares trade at $70.97 with a $12.4 billion market cap.cnbc
Why Long-Term: A rare AI-native healthcare data company with pharma partnerships that could scale into a dominant precision-medicine data moat.
Micron (MU)

Business & Moat: Micron is a critical memory-chip supplier (DRAM/NAND/HBM) for AI servers, benefiting directly from the AI infrastructure memory bottleneck.
Recent Earnings & Catalysts: Trading at $914.21 with a $1.03 trillion market cap and EPS of $45.12, Micron has become one of the biggest beneficiaries of the AI memory supercycle, with HBM demand from Nvidia and hyperscalers driving pricing power.cnbc
Why Long-Term: Structural memory-chip shortage tied to AI training/inference demand supports a multi-year upcycle thesis.
Bitmine Immersion (BMNR)

Business & Moat: Bitmine operates as an Ethereum treasury and crypto-mining/immersion-cooling infrastructure company, giving investors leveraged exposure to Ethereum’s price and adoption.
Recent Earnings & Catalysts: Shares trade at $26.36 with a $15.0 billion market cap; earnings have been volatile, reflecting crypto-treasury mark-to-market swings.cnbc
Why Long-Term: A high-beta proxy on Tom Lee’s bullish Ethereum thesis (targets of $7,000-$9,000 near-term, with tokenization/payments as long-term drivers).finance.yahoo

CRISPR Therapeutics (CRSP)
Business & Moat: CRISPR Therapeutics is a gene-editing pioneer with Casgevy, an approved therapy for sickle cell disease and beta-thalassemia, plus a broad pipeline in oncology and diabetes.

Recent Earnings & Catalysts: Q2 2026 revenue of $10.2 million beat the $7.4 million estimate; shares trade at $59.99 with a $5.79 billion market cap.cnbc
Why Long-Term: First-mover advantage in CRISPR-based gene editing gives long-term optionality across a huge range of genetic diseases, though commercialization remains early and cash-burn intensive.

Bloom Energy (BE)

Business & Moat: Bloom Energy manufactures solid-oxide fuel cells for on-site power generation, increasingly positioned as a fast-deploy power solution for AI data centers facing grid bottlenecks.
Recent Earnings & Catalysts: Q2 2026 revenue of $1.07 billion crushed the $826 million estimate, with EPS of $0.78 versus $0.39 expected — a massive beat driven by data-center power demand; shares trade at $220.01 with a $64.8 billion market cap.cnbc
Why Long-Term: AI data centers need power faster than utilities can build transmission — Bloom’s modular fuel cells fill that gap, a structural tailwind through the decade.
AST SpaceMobile (ASTS)

Business & Moat: AST SpaceMobile is building a satellite constellation offering direct-to-standard-smartphone cellular connectivity, partnering with major telecom carriers globally.
Recent Earnings & Catalysts: Revenue remains small and lumpy (Q2 2026: $31.5 million versus $34.5 million estimate) as the company is still pre-scale, with shares trading at $60.92 and a $24.8 billion market cap pricing in future constellation completion.cnbc

Why Long-Term: A credible challenger to SpaceX’s direct-to-cell ambitions with deep telecom-carrier partnerships — high execution risk but enormous TAM if successful (billions of existing unmodified smartphones).
IonQ (IONQ)
Business & Moat: IonQ builds trapped-ion quantum computers, accessible via AWS, Azure, and Google Cloud, positioning it as a leading pure-play in commercial quantum computing.cnbc
Recent Earnings & Catalysts: Q2 2026 revenue of $80.1 million beat the $66.4 million estimate; shares trade at $42.36 with a $15.8 billion market cap.cnbc
Why Long-Term: Quantum computing remains early-stage and speculative, but IonQ’s multi-cloud distribution gives it a distribution moat as enterprises begin quantum pilots.
Oklo (OKLO)

Business & Moat: Oklo develops the Aurora advanced fission powerhouse (15-75 MW) plus nuclear fuel recycling technology, targeting the same AI-driven power demand surge benefiting Bloom Energy.
Recent Earnings & Catalysts: Shares trade at $43.21 with a $7.52 billion market cap; the company remains pre-revenue commercially but has a strategic partnership with Blykalla for advanced reactor development.cnbc
Why Long-Term: Small modular reactors are increasingly viewed as essential for reliable, carbon-free baseload power for AI data centers — a multi-decade nuclear renaissance thesis.

CrowdStrike (CRWD)
Business & Moat: CrowdStrike’s cloud-native Falcon platform dominates endpoint security, with a broad module ecosystem spanning identity protection, threat intelligence, and log management.
Recent Earnings & Catalysts: Shares surged to $225.84, up nearly 19% in the latest session, pushing the P/E to an extreme ~6,942x — reflecting either a major re-rating catalyst or a low-earnings-base distortion investors should scrutinize closely.cnbc
Why Long-Term: Best-in-class cybersecurity platform with high switching costs and subscription-based recurring revenue in a non-discretionary spending category.
Closing Thought from Coach Kyle
Every name on this list is an “exponential curve” bet — AI, space, crypto, quantum, energy storage, there will be many bumps in the road and most likely a couple black swan events, this is why we need to be obsessed with knowing what we own. We need to continue to build our conviction on a daily basis. Volatility isn’t a bug in this strategy — it’s the toll you pay for exponential upside. Stay patient, stay convicted, and always size positions for the drawdowns, not just the upside.

G.L.A INVE$T RE$EARCH & Coach Kyle — Educational content only. Not investment advice. Not a licensed advisor.