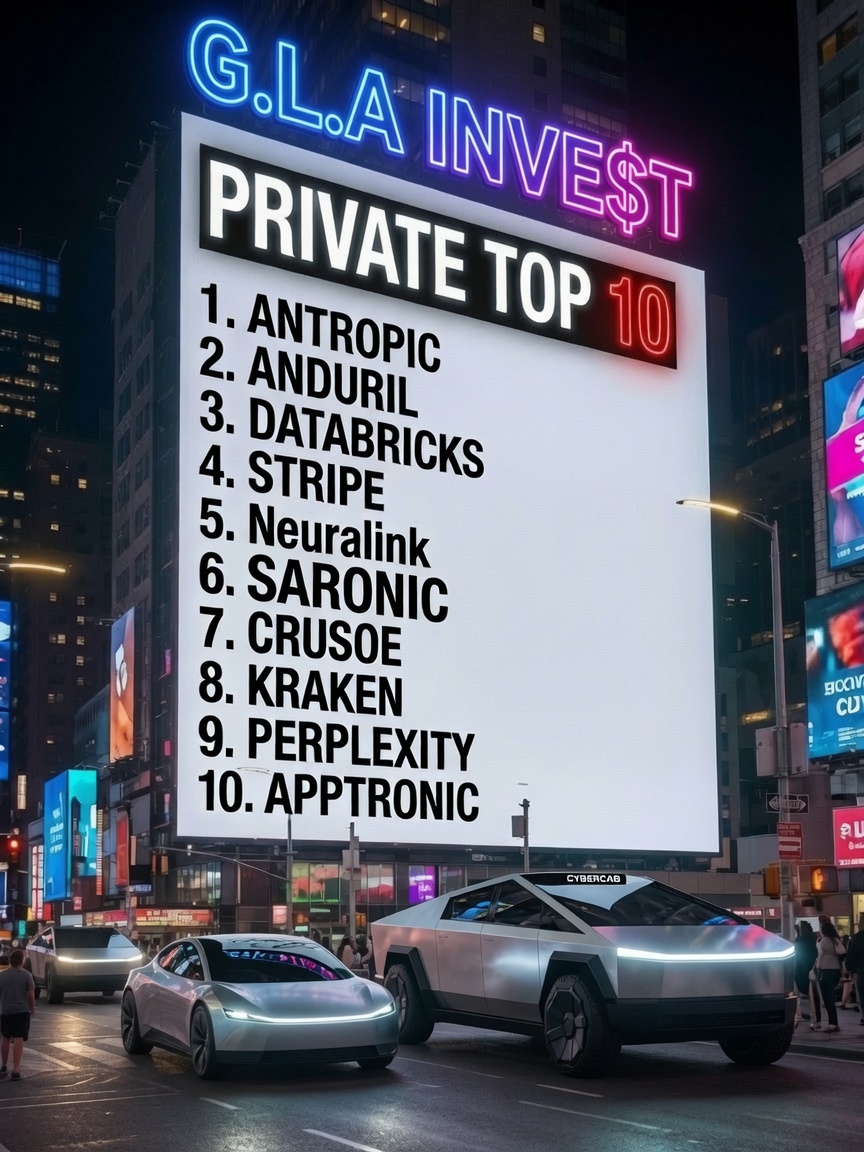
Happy Wednesday to The G.L.A NATION! One of the most important things I want my readers and network to understand is, we are still in the early innings of the largest innovation boom in history—The rise of AI, ROBOTICS, GENOMICS, ENERGY STORAGE and BLOCKCHAIN will mint a new flock of millionaires through longterm investing! Investors who only index public markets risk missing a major share of the value being created in AI, robotics, genomics, energy storage, and blockchain.This newsletter is about how to thoughtfully build a private market pre‑IPO strategy alongside your public portfolio, and why discipline—not gambling—is the key.
Public vs Private Markets: Two Complementary Engines
Public markets (stocks, ETFs, index funds) are liquid, regulated, and accessible. Private markets (pre‑IPO equity, venture, private credit) are illiquid, opaque, and harder to access—but historically have offered higher long‑term returns.
Multiple independent studies show that pre-ipo and venture capital funds have outperformed public equity benchmarks over the last 25+ years, even after fees. Cambridge Associates, MSCI, and others find private equity annualized returns 400–500 bps above broad public indices over decades—meaning a dollar in private equity often compounds to roughly 3x the wealth of the same dollar in public equities across a full cycle.
That does not mean public markets are obsolete. It means:
Investors should build two portfolios:
A Disciplined Longterm public market portfolio (concentrated portfolio (7-10 companies) in diversified companies, longterm 3-5 year time horizon).
A curated private market portfolio (Companies that have proven visionary founders, Companies that are big enough and developed enough to predict with a high degree of probability, companies that are leading areas that are solving problems at scale, AI, Robotics, Genomics, Blockchain and Energy Storage)
Being very picky in both is essential; not every public stock or private deal deserves capital. Knowing what not to invest in is half the battle.
Ways to Access the Pre‑IPO and Private Market
1. Direct secondaries via platforms (e.g., Hiive)
Platforms like Hiive create marketplaces where employees and early investors can sell pre‑IPO shares, and buyers can access late‑stage private companies directly.
Key attributes:
Live order books and price discovery for pre‑IPO names.
Direct share transfers or SPV structures.
Variable fees; some structures eliminate traditional 2/20 fund economics on certain SPVs.
For sophisticated, accredited investors, these platforms can be powerful tools—but due diligence on fees, mark‑ups, and underlying company quality is critical.
2. Private equity / venture funds
Traditional private equity and venture funds pool capital to invest in portfolios of private companies.
For investors evaluating these funds:
Avoid funds that charge high mark‑ups on underlying deals or layer excessive fees (multiple levels of carry, hidden transaction costs).
Prefer proven managers:
Funds with a track record of real liquidity—distributions back to LPs from exits, not just paper marks.
Managers with multiple successful fund vintages, demonstrating repeatable edge across cycles.
Transparent funds with multiple portfolio companies.
The goal is to access the best innovation companies in private markets without handing away the excess return to fee stacks and mark‑ups.
3. Non‑accredited investors: venture‑style mutual funds and RTFs
Historically, non‑accredited investors had almost no access to venture and pre‑IPO opportunities. That is starting to change.
One notable product is the ARK Venture Fund (ARKVX):
Open to both accredited and non‑accredited investors.
Holds a portfolio of private and public innovation names in an RTF (interval/mutual) fund structure.
Provides partial liquidity (e.g., 5% quarterly) while targeting long‑term venture‑like exposure.
There are emerging peers and structures that follow a similar model—like RVI from Robinhood, publicly offered funds that blend public growth with curated private positions. For non‑accredited investors, these vehicles can serve as a gateway to pre‑IPO exposure within a regulated wrapper, though you should carefully evaluate fees, liquidity terms, and concentration risk.
Why Private Markets Have Outperformed
Private markets historically deliver higher returns due to:
Inefficiencies and illiquidity: Private securities often trade at discounts of 20–30% versus similar public assets, compensating investors for illiquidity and complexity.
Active value creation: PE and venture managers can influence strategy, governance, and capital structure directly.
Selection bias: Many of the highest‑growth innovation companies spend most of their life private, going public only after a significant share of value creation has occurred.
Institutional analyses show:
US private equity returns exceeding public indices by ~400–500 bps annually over 20–25 years.
Private equity generating 13%+ net annualized returns vs ~8% for broad public indices over multi‑decade periods.
This is why IRAs and long‑duration capital are particularly well‑suited for private market allocations:
IRAs are already long‑term, making illiquidity less painful.
Tax‑advantaged growth pairs well with higher expected returns.
Risks: Small Private Companies, Interest Rates, and Liquidity
Despite the upside, private pre‑IPO investing carries real risks:
Small companies may never go public: Some promising startups stall, pivot, or die. There is no guarantee of an IPO or acquisition.
Interest rate shocks (like 2022) can crush valuations:
Higher rates raise discount rates, compress multiples.
Funding dries up; companies face down rounds or distressed exits.
Illiquidity: You may be locked in for years. Secondary liquidity is helpful but not guaranteed or always attractive.
Information asymmetry: Less transparency than public markets; financials and metrics may be limited.
Capturing Growth Before the Public Spotlight–Pre-IPO companies are typically late-stage private businesses that have already proven product-market fit, scaled operations, and attracted institutional capital. By the time they file for an IPO, much of their highest-growth phase has often occurred while they were still private. Investors who participate at this stage can benefit from the company’s remaining private-period expansion and any valuation re-rating that accompanies a successful public listing. Historical examples across technology, consumer, and healthcare show that substantial equity value is frequently created in the years immediately preceding an IPO.
Higher Expected Returns and the Illiquidity Premium—Private markets have historically delivered competitive long-term returns relative to public equities, partly because capital is committed for multi-year periods. This “illiquidity premium” compensates investors for locking up funds and forgoing daily liquidity.Venture capital and growth equity strategies, in particular, have produced attractive net returns for limited partners over extended horizons when managers select high-quality companies and support them through scaling. The absence of constant mark-to-market pressure allows management teams to prioritize durable value creation over short-term optics.
Access to Innovation and Category-Defining Companies–Many of the most transformative businesses of recent decades spent years (sometimes more than a decade) as private companies. By investing in the private markets, allocators gain exposure to emerging technologies, business models, and founders before those companies become widely owned public securities.This early access can improve portfolio construction by introducing growth engines that are less correlated with the broader public equity indices
Lower Day-to-Day Volatility and Longer Time Horizons-Private valuations are updated far less frequently than public stock prices.As a result, portfolios with meaningful private allocations tend to experience smoother reported performance. Managers and company leadership can focus on operational milestones, product development, and market expansion rather than reacting to quarterly earnings expectations or activist pressure. This structural difference aligns capital with patient, multi-year strategies—an advantage in industries where compounding requires sustained investment.
A Growing and Increasingly Accessible Opportunity -The private markets have expanded dramatically. More high-quality companies are choosing to remain private longer, supported by deeper pools of institutional capital. At the same time, secondary platforms, specialized funds, and structured vehicles have made late-stage and pre-IPO exposure more accessible to a broader range of qualified investors than in prior decades.
Discipline: Don’t Use Pre‑IPO as Gambling Devices
Our philosophy at G.L.A. INVE$T RE$EARCH:
Pre‑IPO and private market investments are not casinos.
Investors should:
Target high‑conviction names with real revenue, defensible moats, and credible paths to liquidity.
Size positions prudently within their total portfolio.
Focus on durable ownership through and after IPO, not flipping on day one.
Used correctly, pre‑IPO investing is a structural edge and a powerful complement to a disciplined public portfolio. Used recklessly, it becomes expensive entertainment.

Building Dual Portfolios: Public + Private Innovation
We encourage thoughtful investors to:
Build a public market innovation portfolio:
Quality growth equities, dont over diversify, large moats, tams, visionary founders, companies that make must have products and services, companies in the early stages of growth with fortress balance sheets and notable investors.
Sector/thematic exposure to AI, robotics, genomics, energy storage, and blockchain.
Risk management, concentrated portfolio in diversified companies, and an explicit long‑term horizon.
Build a private market portfolio:
Select pre‑IPO and venture names that are big enough and developed enough to predict with a high degree of probability, companies with visionary founders, companies that make must have products and services , large moats, large TAM”S, notable investors with fortress balance sheets
Focus on managers and structures with proven liquidity histories and reasonable fees.
Size allocations within your overall risk tolerance and time horizon.
We are still early in an innovation super‑cycle:
AI and autonomy (software + hardware).
Robotics and industrial automation.
Genomics and precision medicine.
Energy storage, electrification, and grid modernization.
Blockchain‑enabled financial and data infrastructure.
Investors who rely only on index investing, and over diversifying like most investment advisors do, risk systematically under‑weighting these frontier sectors, as many indices are dominated by legacy incumbents and mature mega‑caps. Index exposure is a base layer—not a complete strategy.

G.L.A. INVE$T RE$EARCH Private Market Top 15
Below is a high‑level snapshot of the G.L.A INVE$T RE$EARCH PRIVATE MARKET top 15—our current focus list of frontier innovation companies in the private market. These are strictly for accredited investors and are presented for educational and entertainment purposes only:
Anduril – Autonomous defense systems, sensor fusion, and AI‑driven command and control.
Anthropic – Frontier AI models and safety‑first AI infrastructure.
Databricks – Lakehouse data infrastructure and AI/analytics platform.
Stripe – Global payments, fintech infrastructure, and embedded finance rails.
Neuralink – Brain–computer interfaces, neurotechnology, and human‑machine integration.
Saronic – Autonomous maritime defense vessels and naval production innovation.
Crusoe – Energy‑efficient compute using stranded energy and modular data centers.
Erebor – Next‑generation infrastructure/compute (frontier technology focus).
Kraken – Crypto exchange and digital asset infrastructure.
Perplexity – AI‑native research and answer engine transforming information retrieval.
Apptronik – General‑purpose humanoid robots and industrial automation.
Light Matter – Photonic computing and optical AI acceleration.
Prometheus – Energy/propulsion or climate‑tech frontier (high‑impact hardware/software).
Shield AI – Autonomous aircraft and AI pilots for defense missions.
D‑Matrix & Vulcan Chariot Defense – Specialized AI hardware and advanced defense platforms.
These names represent core themes we believe are central to the next decades of value creation: AI, autonomy, robotics, advanced compute, defense tech, energy, and crypto‑infrastructure.