🔥 G.L.A. INVE$T RESEARCH

PALANTIR $PLTR — THRIVES IN CHAOS
Premium Intelligence for the Bold Investor
March 2026 | Innovation Series | Deep Dive Edition
“The stock market is the only store on earth where the shoppers get scared during a sale.”
— G.L.A. INVE$T RESEARCH
Who We Are
G.L.A. INVE$T is a premium research service built for investors of all sizes. Our mission is to keep our subscribers in the know with breaking news, news translations, scam identification and prevention, and independent perspectives from a Wall Street veteran. Our specialty is innovation — we provide deep-dive research and 24/7 coverage of the top innovation themes of our time.
We believe we are in the first or second inning of an Innovation/Productivity doubleheader that will dwarf the internet. Our investment strategy is a little unconventional — we like to put all of our eggs in just a few baskets, then we watch those baskets very closely. We only invest in companies our research indicates can 10x, 20x, or 30x over the next 5–10 years. We view volatility as vitality. We do not let the finance media or Wall Street dictate our opinions, and we understand that corrections and pullbacks are literally part of this game.

The Greatest Software Earnings. Ever.
Let’s just say it out loud: Palantir’s Q4 2025 earnings were, in our opinion, the greatest earnings report in the history of software companies. Not hyperbole — math.
The numbers speak for themselves. Q4 2025 revenue surged 70% year-over-year to $1.41 billion, the highest growth rate in Palantir’s history as a public company — crushing the Wall Street consensus of $1.33 billion by nearly 6%. Full-year 2025 revenue grew 56% to $4.475 billion. On the bottom line, adjusted EPS came in at $0.25, beating estimates of $0.23. The kicker? 2026 full-year revenue guidance of $7.18–$7.20 billion — implying roughly 60% growth — obliterated analyst projections and reset expectations entirely.
But here’s what really separates this report from everything else:
U.S. Commercial Revenue: Up 137% year-over-year to $507 million — beat estimates by $28 million
U.S. Government Revenue: Up 66% year-over-year to $570 million — beat estimates by $48 million
U.S. total revenue crossed $1 billion for the first time, growing 93% YoY
Adjusted operating income: $798 million at a 57% margin, beating prior guidance by 500 basis points
GAAP net income: $609 million — a 43% margin
Adjusted free cash flow for full-year 2025: $2.27 billion — 51% margin, up 82% YoY
Closed highest TCV quarter ever: $4.3 billion in total contract value, up 138% year-over-year
Deal flow exploded: 180 deals ≥$1M (vs. 104 in Q3 2024); 61 deals ≥$10M
Net dollar retention hit 139% — customers are not just staying, they are spending more
This is not a company growing into its valuation. This is a company that is accelerating into dominance.

The Rule of 40 — PLTR Breaks Physics
The Rule of 40 is the gold standard benchmark for software company health. It adds a company’s revenue growth rate to its profit margin. A score above 40% is considered healthy. A score above 60% is considered elite. Most software giants would celebrate a score of 70–80%.
Palantir scored 127% in Q4 2025.
That is not a typo. One hundred and twenty-seven percent — up 46 points year-over-yearand 13 points quarter-over-quarter, marking the 10th consecutive quarter of expanding Rule of 40 score. To put this in context, Palantir’s Rule of 40 journey went from a trough of approximately 35% in 2022, to 60% in mid-2024, to 94% by Q2 2025, and now to a jaw-dropping 127%. No major enterprise software company at Palantir’s revenue scale has achieved this. This is not a growth company pretending to be profitable — this is a profitability machine that is simultaneously accelerating its growth.

The Chaos Is the Catalyst
While the market has been volatile and headlines have been noisy, Palantir has been cashing checks. Here is the breaking news from the last 30 days that Wall Street’s bears conveniently glossed over:
🛡️ DHS Awards Palantir Up to $1 Billion Contract
The U.S. Department of Homeland Security signed a five-year contract with Palantir, potentially worth up to $1 billion, to deploy its Gotham and Foundry AI platforms across multiple agencies for threat detection, case management, logistics coordination, and emergency response. This is not a pilot program. This is full-scale federal infrastructure.
⚔️ NATO Selects Palantir’s Maven Smart System
NATO’s Allied Command Operations selected Palantir’s Maven Smart System (MSS) for military planning and battlefield AI — deploying across the alliance amid some of the most intense geopolitical tensions in a generation. The same Maven system already embedded across every branch of the U.S. military is now the backbone of NATO’s AI defense strategy.
🏛️ $900M+ in New Federal Contracts
Spanning the Army, ICE, IRS, Space Force, and Treasury Department’s unified API layer, Palantir has secured over $900 million in new federal contracts recently. The Trump administration’s proposed increases in defense spending and its government efficiency initiatives have positioned Palantir as the primary technology partner for federal modernization.
📈 $10 Billion U.S. Army Enterprise Deal
Palantir locked in a 10-year, $10 billion enterprise deal with the U.S. Army — cementing its role as the operating system for America’s military machine.
The company now commands 77% of its revenue from U.S. operations, with the government segment at roughly 55% and commercial at a rapidly growing 45%. The government moat is deep. The commercial acceleration is the new fuel.
Wall Street Will Always Call PLTR Expensive
Let’s address the elephant in the room — because it has been in the room for years and it’s not leaving.
They called it expensive at $10. They called it expensive at $30. They called it expensive at $80. The stock touched $120 after a pullback from highs above $220 in late 2025. yes — analysts are still out there with $50 price targets. Meanwhile, Citi upgraded PLTR to Buy with a $235 target, and the median analyst price target sits around $190.
This is a pattern we have seen before. Wall Street has a long, embarrassing track record of missing transformational innovation companies:
Company | What Wall Street Said | What Actually Happened |
|---|---|---|
Amazon (AMZN) | “It’s a bookstore, wildly overvalued” | Became a $2T+ empire spanning e-commerce, cloud, and AI |
Netflix | “Blockbuster will crush them, P/E is insane” | Reinvented entertainment globally |
Tesla | “Cars are a commodity, this is a meme stock” | Became the most valuable auto company on earth |
Nvidia | “A gaming chip company, too expensive” | The engine of the AI revolution |
Palantir | “Too expensive, government-dependent, no moat” | 127 Rule of 40, 70% revenue growth, NATO + DHS + Army |
Amazon is the blueprint. Early investors in Amazon endured brutal drawdowns and relentless “overvalued” calls from analysts — but those who stayed the course were rewarded beyond imagination. AWS, the cloud business that now prints billions, was built from Amazon’s internal infrastructure and licensed to the world. That is the exact same playbook Palantir is running with AIP — building the AI operating layer internally, proving it in the most demanding environments on earth (war zones, intelligence agencies), and now licensing it to the commercial world at scale.
The market doesn’t reward the crowd. It rewards the patient and the convicted.

The Bottom Line From Our Desk
Palantir is not a trade. It is a position. It is a bet that the United States government, NATO, and the world’s largest corporations will continue to need the most sophisticated AI decision-making platform ever built. It is a bet that the person who built the surveillance infrastructure for the CIA in 2003 has a 20-year head start on every competitor that just started writing AI code in 2022. It is a bet that data + AI + institutional trust = the most durable moat in technology.
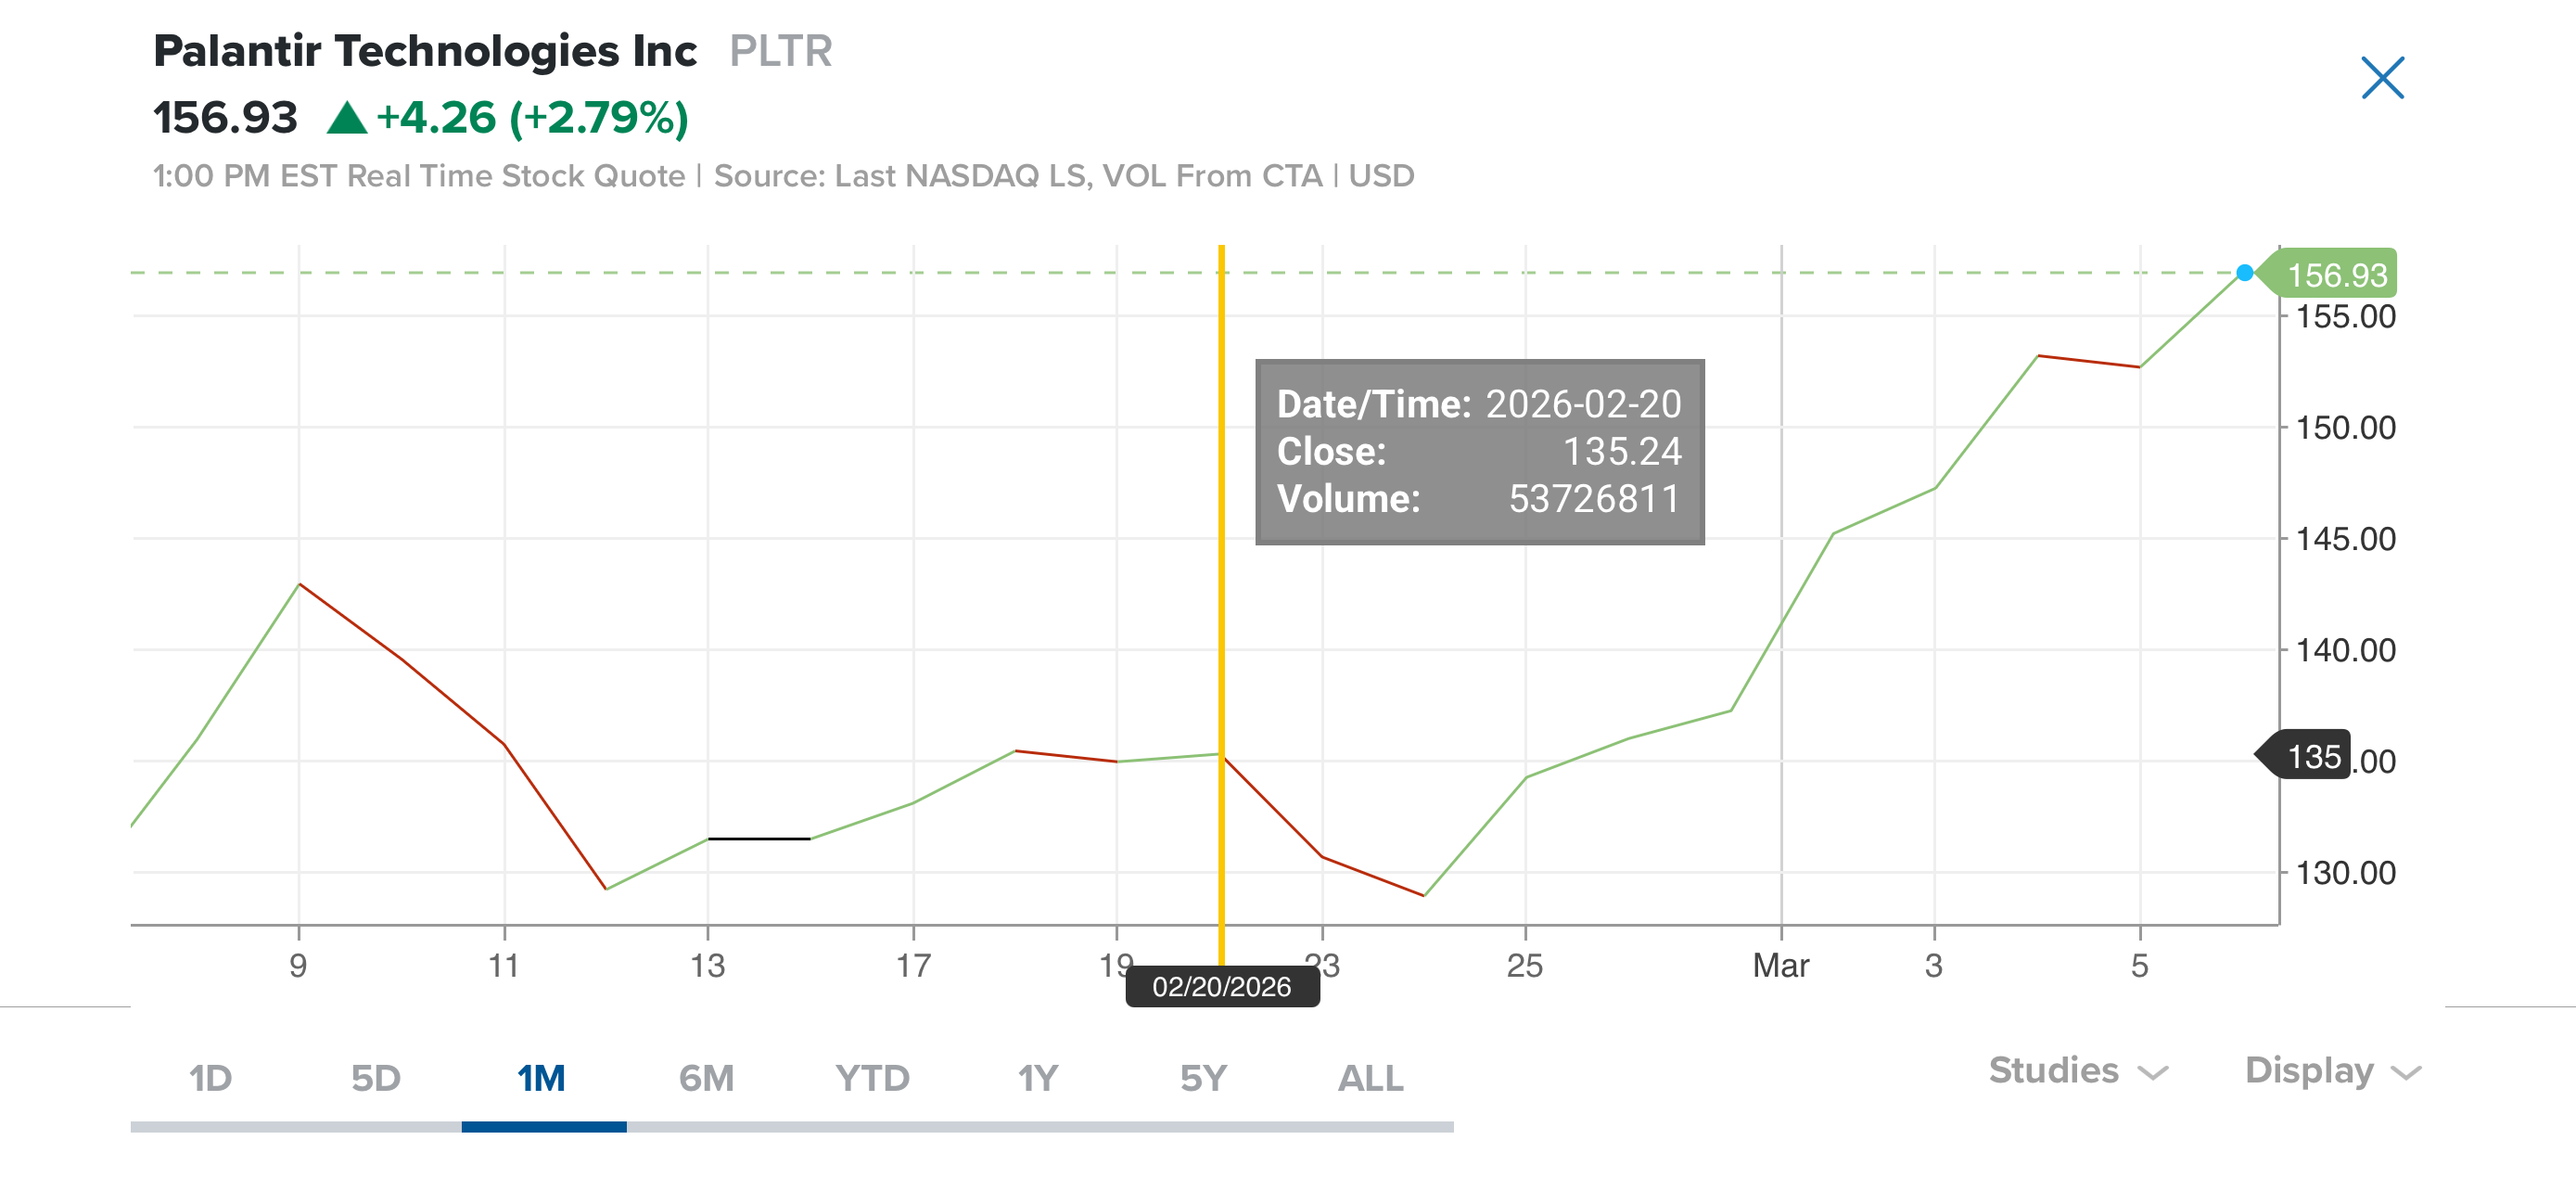
The volatility you see in PLTR’s chart? That is not weakness. That is the price of admission to one of the greatest wealth-building stories of our generation.
At G.L.A. INVE$T, we do not flinch when the market goes on sale. We load up the cart.
“We are in the first or second inning of an Innovation/Productivity doubleheader that will dwarf the internet. Our job is to identify the players that will dominate — Get Ready For the revolution, It Will Be Televised!”
— G.L.A. INVE$T RESEARCH

⚠️ Disclaimer: G.L.A. INVE$T RESEARCH is for informational and educational purposes only. This is not financial advice. All investments involve risk. Do your own due diligence.
📩 Stay locked in. More research dropping soon.
— G.L.A. INVE$T | Premium Innovation Research | 24/7 Coverage

